Brazil is one of the world’s agricultural powerhouses. It’s the largest exporter of soybeans, coffee and sugar, one of the leading producers of corn, cotton and beef, and its agricultural sector plays a critical role in feeding a growing global population.
Less well known is that Brazil is also becoming one of the fastest-growing markets for agricultural technology. The country’s smart agriculture market was valued at approximately US$669 million in 2025 and is expected to more than triple by 2033, driven by the rapid adoption of precision farming, automation, artificial intelligence and data-driven agriculture. Brazil now counts more than 2,000 AgTech companies, which makes it one of the world’s largest agricultural innovation ecosystems.
For European and North American technology companies, that’s a real shift. Brazil is no longer just a destination for agricultural exports or heavy machinery. Advanced software, sensors, automation and digital solutions increasingly play a central role in raising productivity across one of the world’s largest farming industries. But the opportunity isn’t as straightforward as it looks.
Not one single agricultural market
One of the biggest misconceptions among international technology companies is treating Brazilian agriculture as a single market. It’s remarkably diverse. The country spans multiple climate zones, ecosystems and production systems, and the technology needs differ enormously from one region to the next.
In the vast plains of Mato Grosso, large-scale soybean, corn and cotton production dominates. Farms covering tens of thousands of hectares rely more and more on GPS-guided machinery, satellite imagery, autonomous equipment and precision application technologies to run efficiently across huge areas. Further south, states such as Rio Grande do Sul and Paraná focus more on livestock, dairy and mixed farming. Producers there tend to invest in herd management software, animal health monitoring and feed optimisation rather than large-scale autonomous field operations.
Minas Gerais, the leading coffee-producing state, has another technology profile altogether. Coffee growers use digital crop monitoring, irrigation management and data analytics to improve quality, sustainability and yield in a highly competitive export market. In São Paulo, sugarcane and citrus dominate, creating demand for everything from precision harvesting to industrial supply chain optimisation. And along the northeast coast, irrigated fruit production keeps expanding, which raises the importance of water management technologies and climate monitoring.
This distinction matters. Selling agricultural technology in Brazil is rarely about targeting “Brazilian agriculture”. It’s about finding the right production systems, understanding regional challenges and matching your technology to specific operational needs.
Brazil’s AgTech ecosystem is growing
Growing demand has also fuelled the rapid expansion of Brazil’s own innovation ecosystem. More than 2,000 AgTech startups now operate across the country, building solutions for every stage of the agricultural value chain, from precision farming and biological crop protection to robotics and digital farm management.
The ecosystem has matured a lot over the past decade. Many Brazilian AgTech companies now operate at commercial scale, backed by venture capital, research institutions such as Embrapa, and close collaboration with one of the world’s largest agricultural industries.
That changes the competitive landscape. Brazil isn’t a market where agricultural technology still has to be introduced. It’s a mature, fast-moving ecosystem, and foreign companies do best when they complement what already exists with specialised technology and international expertise.
Where international technology creates value
The rapid growth of Brazil’s AgTech sector doesn’t mean the opportunities for international companies have disappeared. Quite the opposite. As the market matures, demand is shifting from basic digitalisation to more specialised technologies that help producers improve productivity, cut operational costs and meet growing sustainability requirements. So the strongest opportunities aren’t in competing head-on with established manufacturers or local software providers, but in complementing them with specialised expertise.
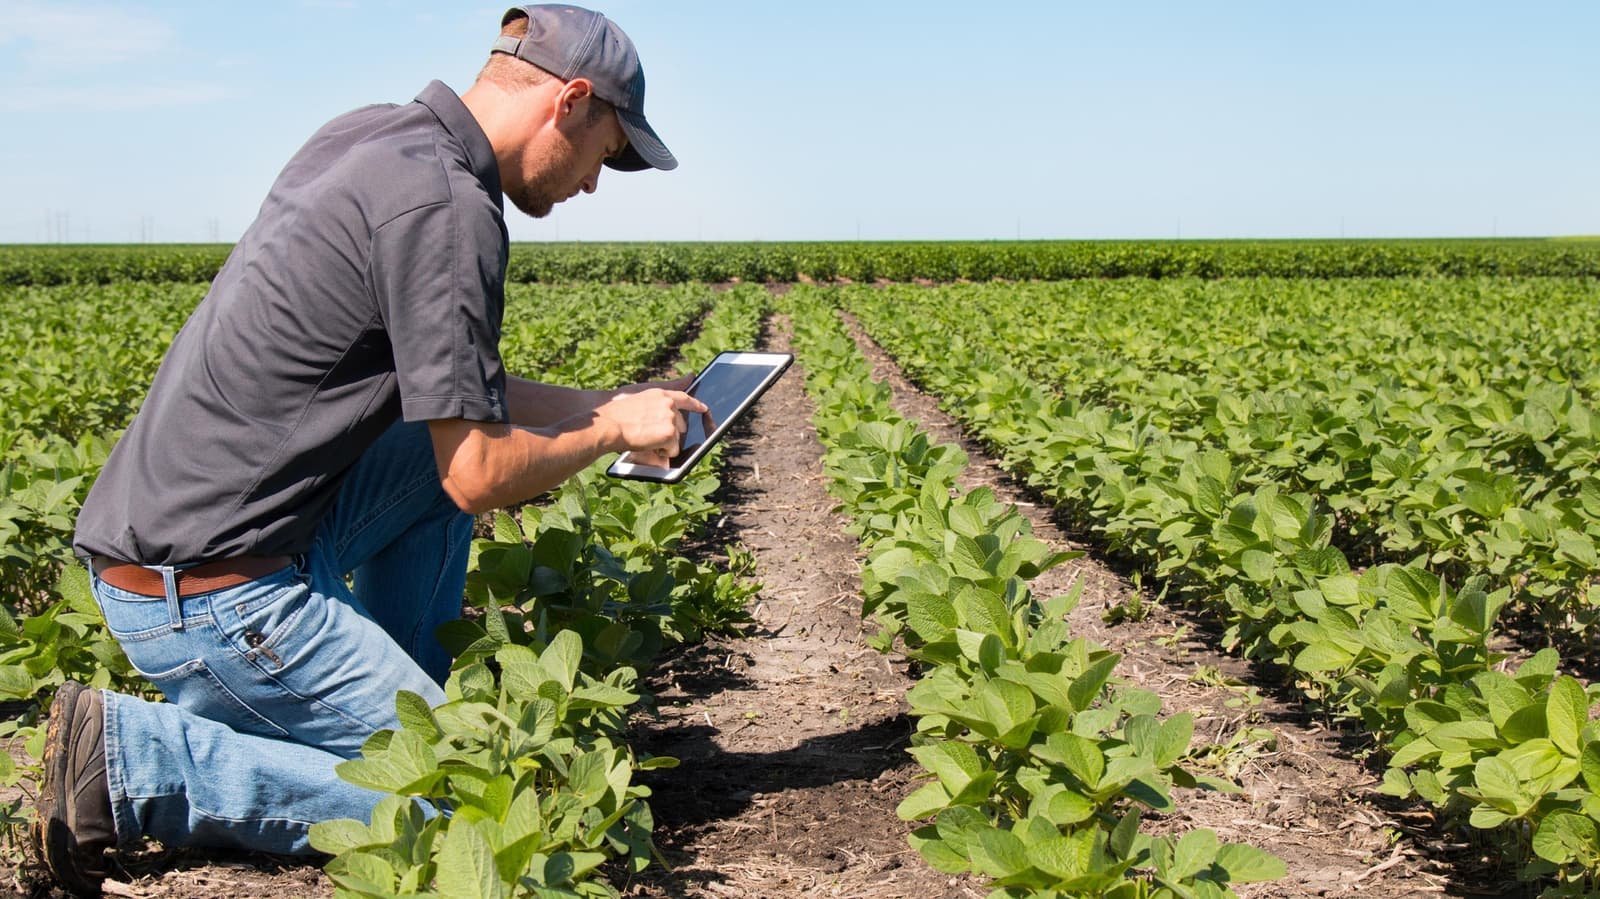
That could mean precision fertiliser and spraying equipment, smart irrigation systems, autonomous guidance, agricultural drones, climate and soil sensors, livestock monitoring, post-harvest automation or farm management software. The technologies differ, but the goal is the same: helping producers increase productivity, reduce input costs and make better-informed decisions.
For European and North American AgTech companies, this means opportunities in both equipment and digital solutions. Brazilian producers are generally willing to invest in technology that shows a clear return. Whether it reduces fertiliser use, improves irrigation efficiency or increases harvesting productivity, a solution to a practical operational problem is usually well received.
Building trust on the ground
Even the most innovative agricultural technology only succeeds if it fits the realities of the Brazilian market. Unlike in many European countries, purchasing decisions in Brazilian agriculture are often built on long-term relationships between producers, distributors, agronomists and equipment suppliers. Showing your technology in the field, providing reliable after-sales support and answering technical questions quickly can matter as much as the technology itself.
For many international AgTech companies, the most effective market entry strategy is therefore gradual rather than immediate. Partnering with established distributors, working with local agronomists, building a network of certified service engineers or exhibiting at regional agricultural fairs all give you valuable market insight and help you build credibility with Brazilian producers.
Local adaptation matters too. Products may need adjustments for tropical climates, different crop varieties, local farming practices or Brazilian technical standards. Commercial materials, technical documentation and customer support are often expected in Portuguese, especially outside the largest multinational agribusinesses.
Over time, this local presence becomes more than an operational necessity. It becomes a competitive advantage. The companies that combine proven international technology with a real understanding of Brazilian agriculture are usually the ones that build lasting relationships and grow sustainably.
Conclusion
Brazil is no longer defined only by the scale of its agricultural production. It’s rapidly becoming one of the world’s largest markets for agricultural technology, driven by digitalisation, automation and the need to produce more efficiently and sustainably.
For international AgTech companies, the opportunity isn’t in treating Brazil as a single market. It lies in understanding its regional diversity, finding the right niche and building a strong local presence. Companies that combine proven technology with local partnerships, reliable support and a long-term market strategy are best placed to benefit from Brazil’s next phase of agricultural modernisation.
At Ipanema International, we help international technology companies explore opportunities in Brazil and build the local foundation they need for sustainable market entry.